Four Ways Your Home Equity Can Work for You
February 21, 2026

You may have heard homeowners today have a lot of equity built up. But what does that really mean? Let’s break it down.


Because your equity isn’t just a number, it’s a powerful asset that can help you take your next big step in life.


How Much Equity Does the Typical Homeowner Have?


Here’s how it works. As you pay down your loan and home prices rise through the years, the share of your home that you own free and clear grows. That’s your equity.


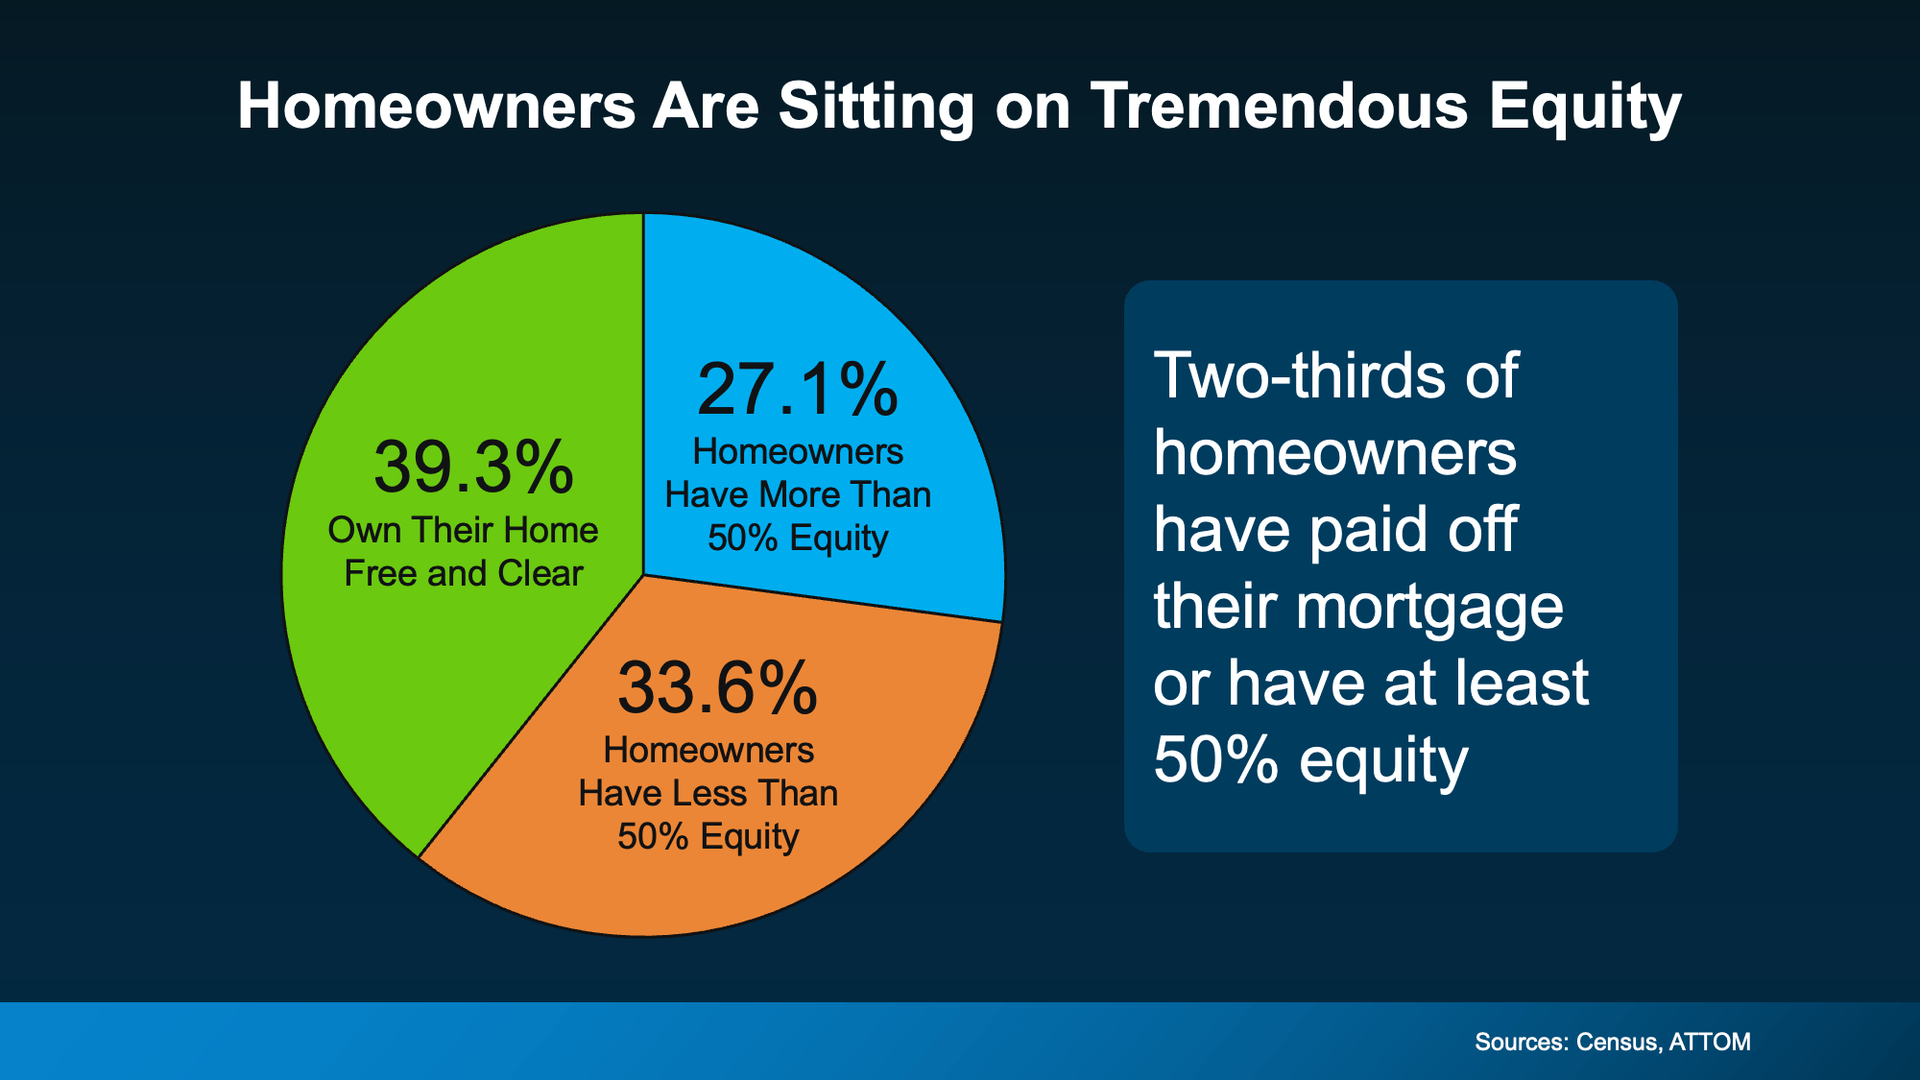
And according to data from the Census and ATTOM, two-thirds of homeowners have a substantial amount of it today.


39% own their home outright without owing anything on it. And another 27% have at least 50% equity in their homes (see chart below):
That’s a big deal. And just in case you’re wondering how that translates into real dollars, Cotality says the typical homeowner has almost $300k in equity today. That’s six figures.


And whether you have that much, even more, or a bit less, here are a few examples of how you can use it. 


Ways You Could Use Your Home Equity


1. Move Into a Home That Better Fits Your Life


Your needs change over time. Maybe your home is starting to feel cramped, or maybe you have more space than you need now that your adult children have moved out. Either way, you can use your equity as a down payment on a home that’s a better fit for what you need now, and going forward. You may even have enough equity to buy your next house in cash.


2. Upgrade Your Current Home


And if you’re not ready to move just yet, you could reinvest it in your current home instead. Renovations like a kitchen refresh or updated bathrooms could add value when it’s time to sell down the line. Just be sure to talk to a real estate agent before you tackle your project list, so you can prioritize updates that’ll give you the biggest return later on.


3. Fund a Major Life Goal


Equity can also help fund your life goals – whether it’s starting a business, saving for retirement, covering education costs, or helping out someone you love. Some homeowners are even passing down some of that wealth to help fund a loved one's down payment on a home.


4. Avoid Foreclosure in Tough Times


If you’re struggling with payments, your equity can also be a lifeline. Many homeowners who hit financial hardships can sell their homes and walk away with money in their pockets instead of facing foreclosure. If that’s something on your mind, talk to a real estate expert about your options and how your equity can help. 


Your Next Steps


If you’re interested in using your equity for one of the reasons above, here’s what to do:


  • Step 1: Ask me for a referral to a specialist that can help with a HELOC and ask me for a personalized equity assessment on your home.
  • Step 2: Start a home equity line of credit. 


Because when it comes to tapping into this resource, there are a few things you’ll want to keep in mind – like making sure you still have a good loan-to-value ratio (LTV) even if you use some of your equity.


That means, as a general rule of thumb, you want to maintain at least 20% equity in your home as a financial cushion – something many homeowners didn’t know back in the crash of 2008.


The good news is, according to the Intercontinental Exchange, most of today’s equity meets that guideline:


“As of Q4, mortgage holders have $17.3T in home equity, including $11.2T in tappable equity ‒ accessible via cash-out refinances or home equity lines while maintaining 20% equity in the property . . . ”


Bottom Line


Your home equity is one of the biggest financial assets you have. Whether you’re thinking about moving, remodeling, or working toward a big goal, it’s worth exploring your options. Please remember, having an equity line gives you peace and security, but there’s no cost to maintain the HELOC if you don’t use any money. It’s like having a savings account that’s accessible if you need it or want it, but interest is not accrued until you use it. 


What’s one goal you have that you'd go after right now, if you had the funds for it?
November 18, 2026
When the homes you love keep landing outside your budget , it may be time to look at the ones other buyers skip. Our very first home was a light fixer in So Cal after I had graduated college. It was a great leaning experience. The house was livable, but super dated, and had no dual pane windows, no Central heat and air, just a wall heater, but it was clean enough to move in. During the 4 years we owned it we took it from under market value, to selling above market value as we put in the new HVAC, we redid the Stucco, put in the windows, and we did so much more. It was fun, and we grew from the experience both emotionally and financially. Plus, it helped me gain the knowledge I have today to help my clients with their homes. A fixer-upper won't be the right call for everyone. Plenty of buyers want a home that's ready on move-in day. But homes that need some updating could get you in the door for a lot less . More buyers are starting to realize it too. And Danielle Hale, Chief Economist at Realtor.com , explains why: “ Fixer-uppers give buyers a way to break into the housing market at a time when affordability is still stretched thin. For those with the vision. . . fixer-uppers provide both a starting point in the market and the chance to create a home that's truly their own.” If that sounds like you, here's why a fixer-upper could be worth a closer look. The Price Tag Is Usually Lower Because these homes need work, they tend to have a lower asking price up front. According to AmeriSave, fixer-uppers usually sell for 20% to 30% less than what they're worth on the market. Here's what that could look like. KCM applied a 25% discount – the middle of that range – to the median home price from the National Association of Realtors (NAR). This is an example, not the average price of a fixer-upper. But it shows the savings could top $100,000 (see graph below):
November 7, 2026
Quick, what credit score do you need to buy a home ? If a number pops into your head, there's a pretty good chance it's wrong. And the right answer is getting harder to pin down, because the way credit scores are determined and delivered is changing - for the better. Here's what you need to know in today's changing credit climate. #1 Most People Are Guessing Fannie Mae has been tracking consumer perceptions about mortgage requirements since 2015 and found that consumers consistently overestimated the minimum credit score lenders required to qualify for a mortgage. As recently as 2023, the average guess was 652. In reality, the long-standing benchmark for loans backed by Fannie Mae and Freddie Mac is lower, at 620, and today even that isn't a hard rule for every mortgage they back. Like the Fannie Mae research, a recent survey from Veterans United found consumers continue to overestimate what it takes to qualify for a home loan: 
November 3, 2026
When you’re planning a move , every monthly cost counts. That’s why it can be frustrating to see home insurance keep creeping up. According to Intercontinental Exchange, it now makes up 9.6% of the average monthly mortgage payment. But the latest numbers show some progress on that front – as the increases start to slow down. Here’s what you need to know and what you can do about it. Premiums Are Rising More Slowly Now A look at the past two years shows how much things have cooled down. In mid-2024, home insurance premiums rose 4.3% in a single quarter. By the second quarter of this year, that was down to 1.8%. That’s the smallest quarterly growth in almost 3 years – and that’s a good thing (see graph below):
October 31, 2026
When mortgage rates climb, buying a home can start to feel like trying to hit a moving target. Every jump in rates makes monthly payments bigger, and that pushes a lot of buyers to look for another way in. More and more of them are finding it in the adjustable-rate mortgage , or ARM. The ARM Option Here’s how an ARM differs from a more traditional mortgage. With a regular fixed-rate mortgage , your rate stays the same for your whole loan. But with an ARM , your rate is locked for the first few years, then it can move up or down based on market conditions . Some people don’t like that level of uncertainty – and that’s okay. But others are drawn to this option specifically because there’s usually a lower rate to start when you opt for an ARM. And in an affordability-strapped market, that’s going to gain popularity. Bankrate recently found that, in September, rates for ARM products were over a full percentage point lower than a regular fixed-rate loan. Depending on the ARM product, that can make a difference of $150-300 in the monthly payment on a median-priced home. And for some buyers, that’s enough to turn “not right now” into “let’s do this.” You can see it in the numbers. Data from the Mortgage Bankers Association (MBA) shows that, in October, roughly 1 in 10 people applying for a mortgage chose an ARM (see graph below): 
October 27, 2026
Here's something most homebuyers don't think about. When the housing market slows down , homeowners and builders don't always respond the same way. Think about it. If you're selling your house and aren't getting the offers you want, you could make the choice to take it off the market and stay put, and wait for things to improve. But builders ? They may be more motivated to stay the course. They've already invested money in building those houses. And every completed home that sits unsold means money tied up in a property, plus ongoing costs that can add up. That's why some builders may be more motivated to negotiate right now. And that could work in your favor. Fewer Buyers Are Making Moves. And Builders Are Feeling It. You’ve probably seen the headlines. According to the latest report from the National Association of Realtors (NAR), pending home sales – homes that have gone under contract but haven't closed yet – fell 7.3% in September and 11.3% compared to last year. Why? Higher mortgage rates are making it harder for buyers to make the numbers work. Now, that report tracks existing homes, not new construction. But we're seeing signs of the same slowdown on the builder side, too. According to the National Association of Home Builders (NAHB), builder confidence dropped to 29 in October , its lowest level since June 2012. Traffic from prospective buyers also dropped to its lowest level in more than a decade, excluding the start of the pandemic. 
October 24, 2026
What's the biggest payment you make every month? If you’re a renter , it's probably your rent. But did you know that you can pay your rent on time, every time, for years, and it may never show up in your credit history? It's pretty frustrating, especially if you'd like to buy a home someday and you’re trying to build your credit. The good thing is that’s changing right now. Here’s what you need to know and why it could open a door you thought was closed. The Problem for Would-Be Buyers You’re not the only one frustrated. According to Zillow, nearly a third of applicants (32.88%) get denied a mortgage due to insufficient credit history - not missed payments or too much debt. Just not enough credit history for a lender to say "yes." It’s the most common hurdle would-be buyers have. As Zillow explains: "Nearly one-third of mortgage applicants are denied a loan because of insufficient credit history , making it the most common reason for a denial .” 
October 21, 2026
When you picture buying your first home , chances are you’re imagining a traditional single-family house with its own yard, maybe a garage, and little extra room to grow. But with affordability still tight, getting everything on that list right away may come with a higher price tag than you’re comfortable with right now. So, if you’re running the numbers and buying a house like that feels like a stretch, there may be another way in. A condo. Because in a lot of markets, condos come with a significantly lower price tag. And that could make them a smart way to get your foot in the door. Condos Can Cost Less Than You Think According to a recent study by Zillow: “ Condos are the most commonly affordable home type in virtually every metro. At the starter level, the savings can be pretty significant. Nationally, starter condos average $197,468 — that’s about 6% less than the typical starter home. ” And depending on where you live, the difference can be much bigger. Zillow identified metro areas where typical starter condos are priced significantly below the estimated home price a median-income household could afford. Here are the top 10 according to that research ( see chart below ). In Houston, the gap is at its widest. There, a typical starter condo was valued at about $85,600 – 72% below the price considered affordable based on the area's median household income. 
October 17, 2026
You've spent years making your house feel like home, celebrating milestones, making each room your own, and turning neighbors into friends. As you look ahead to the next chapter of your life, it's natural to wonder if this is still the place you want to spend it. Whether you're leaning toward staying in your house as you get older or moving to a 55+ community, the goal is the same: a home that fits the life you want, with more time for the people and things you love. So, here's what to consider before you decide. What It Can Take To Stay Put Wanting to stay in a house you love and are familiar with makes sense. But most houses need at least some updates to make aging in place easier. In fact, the Joint Center for Housing Studies of Harvard University (JCHS) finds that fewer than 4% of homes have the basics, like single-floor living, no-step entries, and wide hallways and doorways (see graph below): 
October 13, 2026
With everything going on, it’s understandable if you’re wondering if you’d regret buying right now. Everyday expenses cost more. Mortgage rates are higher than you’d like. And when the economy feels uncertain, taking on a mortgage can feel like a much bigger leap. But here’s some perspective that may help… Most people who already made that leap would do it again. According to a recent survey from NerdWallet, the vast majority of recent buyers (74%) were glad they bought their current home. Only a very small 3% of people regret it: 
October 10, 2026
Higher mortgage rates don't just affect buyers. They can change what it takes to sell your house, too. That's because today's buyers are paying close attention to affordability. And when rates rise, even a relatively small change can make a noticeable difference in their monthly payment. So, they're looking for ways to make the numbers work. And in some markets, new construction is giving them exactly that. If you're planning to sell , that doesn't mean you can't compete. But it does mean you need to understand what builders are doing to win over buyers – and what options you have, too. Builders Are Competing on the Monthly Payment New construction has something interesting going for it right now. While existing-home sales (homes that have previously been lived in, resale homes) continue to sell, the dated, or not updated ones tend to struggle under the weight of higher mortgage rates, new-home sales are holding up a bit better. Buyers in this market are very picky and don't over pay for a house that needs work. In a recent interview , Logan Mohtashami, Chief Economist at HousingWire explains new-home sales are at an 8-month high and are now running around 2019 levels . On the flip side, existing home sales are lagging behind and fall about 1 million home sales short of 2019 levels. One big reason builders have been able to navigate higher rates differently is incentives. According to Realtor.com , nearly 1 in 5 (18.8%) newly built homes come with some kind of buyer incentive advertised up front, here in Placer and Sacramento county I have seen 100% of the builders are offering some kind of incentives to the buyers of the standing inventory. 
Show More
November 18, 2026
When the homes you love keep landing outside your budget , it may be time to look at the ones other buyers skip. Our very first home was a light fixer in So Cal after I had graduated college. It was a great leaning experience. The house was livable, but super dated, and had no dual pane windows, no Central heat and air, just a wall heater, but it was clean enough to move in. During the 4 years we owned it we took it from under market value, to selling above market value as we put in the new HVAC, we redid the Stucco, put in the windows, and we did so much more. It was fun, and we grew from the experience both emotionally and financially. Plus, it helped me gain the knowledge I have today to help my clients with their homes. A fixer-upper won't be the right call for everyone. Plenty of buyers want a home that's ready on move-in day. But homes that need some updating could get you in the door for a lot less . More buyers are starting to realize it too. And Danielle Hale, Chief Economist at Realtor.com , explains why: “ Fixer-uppers give buyers a way to break into the housing market at a time when affordability is still stretched thin. For those with the vision. . . fixer-uppers provide both a starting point in the market and the chance to create a home that's truly their own.” If that sounds like you, here's why a fixer-upper could be worth a closer look. The Price Tag Is Usually Lower Because these homes need work, they tend to have a lower asking price up front. According to AmeriSave, fixer-uppers usually sell for 20% to 30% less than what they're worth on the market. Here's what that could look like. KCM applied a 25% discount – the middle of that range – to the median home price from the National Association of Realtors (NAR). This is an example, not the average price of a fixer-upper. But it shows the savings could top $100,000 (see graph below):
November 7, 2026
Quick, what credit score do you need to buy a home ? If a number pops into your head, there's a pretty good chance it's wrong. And the right answer is getting harder to pin down, because the way credit scores are determined and delivered is changing - for the better. Here's what you need to know in today's changing credit climate. #1 Most People Are Guessing Fannie Mae has been tracking consumer perceptions about mortgage requirements since 2015 and found that consumers consistently overestimated the minimum credit score lenders required to qualify for a mortgage. As recently as 2023, the average guess was 652. In reality, the long-standing benchmark for loans backed by Fannie Mae and Freddie Mac is lower, at 620, and today even that isn't a hard rule for every mortgage they back. Like the Fannie Mae research, a recent survey from Veterans United found consumers continue to overestimate what it takes to qualify for a home loan: 
November 3, 2026
When you’re planning a move , every monthly cost counts. That’s why it can be frustrating to see home insurance keep creeping up. According to Intercontinental Exchange, it now makes up 9.6% of the average monthly mortgage payment. But the latest numbers show some progress on that front – as the increases start to slow down. Here’s what you need to know and what you can do about it. Premiums Are Rising More Slowly Now A look at the past two years shows how much things have cooled down. In mid-2024, home insurance premiums rose 4.3% in a single quarter. By the second quarter of this year, that was down to 1.8%. That’s the smallest quarterly growth in almost 3 years – and that’s a good thing (see graph below):
October 31, 2026
When mortgage rates climb, buying a home can start to feel like trying to hit a moving target. Every jump in rates makes monthly payments bigger, and that pushes a lot of buyers to look for another way in. More and more of them are finding it in the adjustable-rate mortgage , or ARM. The ARM Option Here’s how an ARM differs from a more traditional mortgage. With a regular fixed-rate mortgage , your rate stays the same for your whole loan. But with an ARM , your rate is locked for the first few years, then it can move up or down based on market conditions . Some people don’t like that level of uncertainty – and that’s okay. But others are drawn to this option specifically because there’s usually a lower rate to start when you opt for an ARM. And in an affordability-strapped market, that’s going to gain popularity. Bankrate recently found that, in September, rates for ARM products were over a full percentage point lower than a regular fixed-rate loan. Depending on the ARM product, that can make a difference of $150-300 in the monthly payment on a median-priced home. And for some buyers, that’s enough to turn “not right now” into “let’s do this.” You can see it in the numbers. Data from the Mortgage Bankers Association (MBA) shows that, in October, roughly 1 in 10 people applying for a mortgage chose an ARM (see graph below): 
October 27, 2026
Here's something most homebuyers don't think about. When the housing market slows down , homeowners and builders don't always respond the same way. Think about it. If you're selling your house and aren't getting the offers you want, you could make the choice to take it off the market and stay put, and wait for things to improve. But builders ? They may be more motivated to stay the course. They've already invested money in building those houses. And every completed home that sits unsold means money tied up in a property, plus ongoing costs that can add up. That's why some builders may be more motivated to negotiate right now. And that could work in your favor. Fewer Buyers Are Making Moves. And Builders Are Feeling It. You’ve probably seen the headlines. According to the latest report from the National Association of Realtors (NAR), pending home sales – homes that have gone under contract but haven't closed yet – fell 7.3% in September and 11.3% compared to last year. Why? Higher mortgage rates are making it harder for buyers to make the numbers work. Now, that report tracks existing homes, not new construction. But we're seeing signs of the same slowdown on the builder side, too. According to the National Association of Home Builders (NAHB), builder confidence dropped to 29 in October , its lowest level since June 2012. Traffic from prospective buyers also dropped to its lowest level in more than a decade, excluding the start of the pandemic. 
October 24, 2026
What's the biggest payment you make every month? If you’re a renter , it's probably your rent. But did you know that you can pay your rent on time, every time, for years, and it may never show up in your credit history? It's pretty frustrating, especially if you'd like to buy a home someday and you’re trying to build your credit. The good thing is that’s changing right now. Here’s what you need to know and why it could open a door you thought was closed. The Problem for Would-Be Buyers You’re not the only one frustrated. According to Zillow, nearly a third of applicants (32.88%) get denied a mortgage due to insufficient credit history - not missed payments or too much debt. Just not enough credit history for a lender to say "yes." It’s the most common hurdle would-be buyers have. As Zillow explains: "Nearly one-third of mortgage applicants are denied a loan because of insufficient credit history , making it the most common reason for a denial .” 
October 21, 2026
When you picture buying your first home , chances are you’re imagining a traditional single-family house with its own yard, maybe a garage, and little extra room to grow. But with affordability still tight, getting everything on that list right away may come with a higher price tag than you’re comfortable with right now. So, if you’re running the numbers and buying a house like that feels like a stretch, there may be another way in. A condo. Because in a lot of markets, condos come with a significantly lower price tag. And that could make them a smart way to get your foot in the door. Condos Can Cost Less Than You Think According to a recent study by Zillow: “ Condos are the most commonly affordable home type in virtually every metro. At the starter level, the savings can be pretty significant. Nationally, starter condos average $197,468 — that’s about 6% less than the typical starter home. ” And depending on where you live, the difference can be much bigger. Zillow identified metro areas where typical starter condos are priced significantly below the estimated home price a median-income household could afford. Here are the top 10 according to that research ( see chart below ). In Houston, the gap is at its widest. There, a typical starter condo was valued at about $85,600 – 72% below the price considered affordable based on the area's median household income. 
October 17, 2026
You've spent years making your house feel like home, celebrating milestones, making each room your own, and turning neighbors into friends. As you look ahead to the next chapter of your life, it's natural to wonder if this is still the place you want to spend it. Whether you're leaning toward staying in your house as you get older or moving to a 55+ community, the goal is the same: a home that fits the life you want, with more time for the people and things you love. So, here's what to consider before you decide. What It Can Take To Stay Put Wanting to stay in a house you love and are familiar with makes sense. But most houses need at least some updates to make aging in place easier. In fact, the Joint Center for Housing Studies of Harvard University (JCHS) finds that fewer than 4% of homes have the basics, like single-floor living, no-step entries, and wide hallways and doorways (see graph below): 
October 13, 2026
With everything going on, it’s understandable if you’re wondering if you’d regret buying right now. Everyday expenses cost more. Mortgage rates are higher than you’d like. And when the economy feels uncertain, taking on a mortgage can feel like a much bigger leap. But here’s some perspective that may help… Most people who already made that leap would do it again. According to a recent survey from NerdWallet, the vast majority of recent buyers (74%) were glad they bought their current home. Only a very small 3% of people regret it: 
October 10, 2026
Higher mortgage rates don't just affect buyers. They can change what it takes to sell your house, too. That's because today's buyers are paying close attention to affordability. And when rates rise, even a relatively small change can make a noticeable difference in their monthly payment. So, they're looking for ways to make the numbers work. And in some markets, new construction is giving them exactly that. If you're planning to sell , that doesn't mean you can't compete. But it does mean you need to understand what builders are doing to win over buyers – and what options you have, too. Builders Are Competing on the Monthly Payment New construction has something interesting going for it right now. While existing-home sales (homes that have previously been lived in, resale homes) continue to sell, the dated, or not updated ones tend to struggle under the weight of higher mortgage rates, new-home sales are holding up a bit better. Buyers in this market are very picky and don't over pay for a house that needs work. In a recent interview , Logan Mohtashami, Chief Economist at HousingWire explains new-home sales are at an 8-month high and are now running around 2019 levels . On the flip side, existing home sales are lagging behind and fall about 1 million home sales short of 2019 levels. One big reason builders have been able to navigate higher rates differently is incentives. According to Realtor.com , nearly 1 in 5 (18.8%) newly built homes come with some kind of buyer incentive advertised up front, here in Placer and Sacramento county I have seen 100% of the builders are offering some kind of incentives to the buyers of the standing inventory. 
Show More