Most Experts Are Not Worried About a Recession

November 28, 2025

Homebuyers are watching the economy closely, and for good reason. Buying a home is one of the biggest purchases most people ever make. And some recession talk in the media has made a lot of would-be buyers second guess their plans.


In the latest LendingTree survey, almost 2 in 3 Americans said they think a recession is coming. And 74% of respondents say that's having an impact on their financial decisions.


But here’s the good news: the experts aren’t nearly as concerned.


Most Americans Expect a Recession, But Most Experts Don’t


According to an October report from the Wall Street Journal (WSJ), only 1 in 3 experts surveyed say we may be headed for a recession sometime in the next 12 months (see graph below):
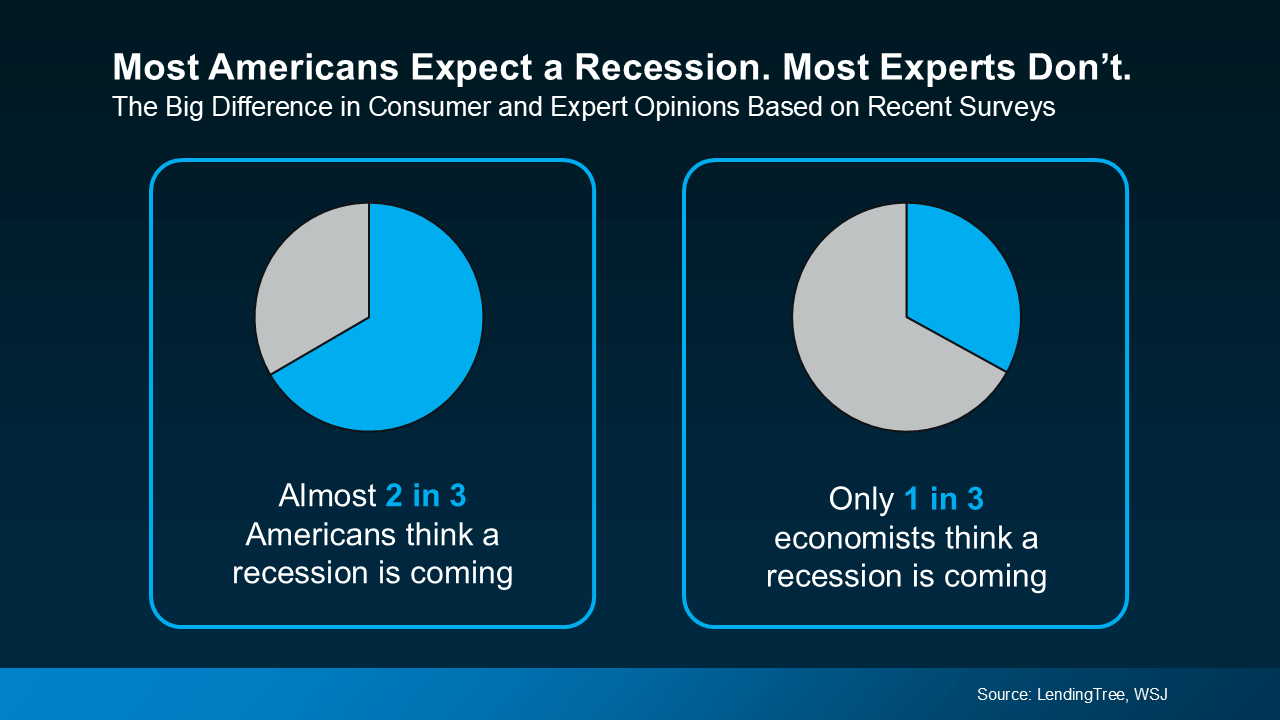
If the expert economists aren’t super worried, should you be? We’re not in a recession right now. And there’s no guarantee we’re heading into one.


What we do have is uncertainty – and the best way to handle that is by leaning on facts, not fear. You can do that by making sure you have the information you need to make an informed decision.


Tips for Buying a Home During Periods of Economic Uncertainty


Here’s the best advice anyone can give right now. While it’s important to keep an eye on what’s happening in the economy, that shouldn’t necessarily overshadow your real-life needs. Economic shifts come and go, but the reasons people buy homes rarely change. Danielle Hale, Chief Economist at Realtor.com, explains:


“Well-prepared buyers who have been waiting on the sidelines are likely motivated by personal and lifestyle needs like growing families, new jobs, or retirement. And these considerations can outweigh short-term economic uncertainties . . . ”


Timing your move around real life (not the news cycle) is what matters most.


But here’s the key. If you're going to buy a home right now, job stability really matters. You need to feel confident in your income and know you can comfortably manage your mortgage payments, even if your situation or the economy shift.


If your job is secure and you’ve built a cushion of savings, experts say you don’t necessarily need to delay. Just keep these tips from the economists at Redfin in mind:


  • Set a budget and stick to it: Don't overextend. Make sure your payments are affordable and your savings can cover any surprises. This includes factoring in costs likely to rise, like home insurance and taxes.
  • Negotiate: There are more homes for sale right now, and other buyers may pull back because of their own fears. That gives you more negotiating power when working with sellers. Use it to get the best deal possible.
  • Be strategic about payments and mortgage rates: Talk to lenders about what payment you can afford and the rate you can qualify for today, as well as your options if rates go down later on.
  • Consider selling before you buy: If you already own a home, selling first can reduce the financial pressure and help solidify your budget for your next home.


But nothing replaces the value of having a trusted team around you, especially right now. As Bankrate says:


"Buying a home during a recession can sometimes be a good idea – but only for people who are lucky enough to remain financially stable . . . Be sure to enlist the help of an experienced local real estate agent. Not only do agents know their markets well, they will also work to get you the best deal in any given situation, including a recession .”


Bottom Line


Most Americans think a recession is coming. But most experts don’t.


So, you don’t necessarily have to put your moving plans on hold. If your finances are solid, your job is stable, and you have a real need to move, you can still make it happen. 


What’s holding you back from making your next move? Let’s talk it over. 
October 10, 2026
Higher mortgage rates don't just affect buyers. They can change what it takes to sell your house, too. That's because today's buyers are paying close attention to affordability. And when rates rise, even a relatively small change can make a noticeable difference in their monthly payment. So, they're looking for ways to make the numbers work. And in some markets, new construction is giving them exactly that. If you're planning to sell , that doesn't mean you can't compete. But it does mean you need to understand what builders are doing to win over buyers – and what options you have, too. Builders Are Competing on the Monthly Payment New construction has something interesting going for it right now. While existing-home sales (homes that have previously been lived in, resale homes) continue to sell, the dated, or not updated ones tend to struggle under the weight of higher mortgage rates, new-home sales are holding up a bit better. Buyers in this market are very picky and don't over pay for a house that needs work. In a recent interview , Logan Mohtashami, Chief Economist at HousingWire explains new-home sales are at an 8-month high and are now running around 2019 levels . On the flip side, existing home sales are lagging behind and fall about 1 million home sales short of 2019 levels. One big reason builders have been able to navigate higher rates differently is incentives. According to Realtor.com , nearly 1 in 5 (18.8%) newly built homes come with some kind of buyer incentive advertised up front, here in Placer and Sacramento county I have seen 100% of the builders are offering some kind of incentives to the buyers of the standing inventory. 
October 6, 2026
For a lot of first-time buyers, owning a home can feel perpetually a few years out of reach. Saving for a down payment takes time, and each year you spend renting can make owning feel further off. But buying your first home doesn’t have to happen to feel like a far away goal. Two choices you control can bring your first home years closer, even with affordability as tight as it is right now. How Long Buying Really Takes First, one quick definition. "Breaking even" is the point where owning has cost you about the same as renting would have over the same period. And after that point, owning starts to cost less than renting. Kara Ng, Senior Economist at Zillow, puts it this way: "Buyers should think about not just when they can afford to buy, but how long they'd need to stay before owning makes more financial sense than renting." So how long does reaching that point usually take? And what are the shortcuts? Let’s do the math. According to Zillow, it usually takes about 8.5 years to save for a 20% down payment, then roughly 6.2 more years before owning costs the same as renting. Together, that's just under 15 years. But that math relies on two assumptions: that you're buying a mid-priced home, and that you're putting 20% down. Change either one and your timeline gets shorter. Change both and it can shrink fast. It also varies widely by market, since local prices and rents are different depending on where you live. A Starter Home Can Get You There Twice as Fast A starter home usually means a home in the lower third of local prices. They’re often condos , townhomes, or single-family homes a little smaller or older than others in the area. Choosing one over a mid-priced home can cut your wait down by a lot. And while that might sound obvious, you may not realize just how much it shortens your timeline. Because if you’re buying a more affordable home, you don’t have to save up as much or as long. Zillow found that nationwide, a starter home takes half the time – about 7.2 years – to save for and come out ahead on, compared with renting (see graph below): 
October 3, 2026
Price cuts are turning up everywhere right now, and they read very differently depending on which side of the deal you’re on. Sellers tend to worry a cut means walking away with less than they hoped. Sometimes that’s true, but more often it just means the market moved faster than the listing did. Buyers , for their part, often assume a cut means something’s wrong with the house. Most of the time, that’s not it. This is what's actually driving all those price cuts, and why it matters no matter which side of the deal you're on. 42% of Homes for Sale Are Now Carrying a Price Cut According to HousingWire Data , the share of sellers cutting their asking price has climbed every month for 7 straight months (see chart below):
September 29, 2026
You may have seen the headlines saying mortgage rates have climbed to the highest point since January 2025. And if that's left you reluctant to buy a home, here's what you need to remember… That's not necessarily the number you'd get. It's a common misconception that the rate you see in the headlines is the same one you'd get when you buy. The truth is, mortgage rates shift often, and the rate you actually end up with can vary a lot from what you may see or hear about. What Determines Your Real Rate? Advertised rates and “real rates” aren’t always the same. That’s because real rates are based on your specific situation, which includes your overall finances and goals. The rates you see in the headlines can’t possibly reflect that. That’s why only a lender can tell you what your real rate will be. To figure out your unique number, they’ll look at: Your credit score : Your credit score includes your payment history (if you’ve made late payments – and how often), credit utilization (are your accounts maxed out, or do you have available credit?), and the length of your credit history (how long have your accounts been open?). For example, someone with an exceptional credit score may qualify for a better rate. Your debt-to-income ratio (DTI) : This is calculated by dividing your monthly debt payments by your monthly income before taxes to come up with a percentage. The higher your DTI, the higher your rate could be. The down payment size and Loan-to-Value (LTV): Your down payment is the percentage of the home’s price you will put down. The LTV is the percentage of a home’s sales price that equals your mortgage. The type and term of loan program options: Your loan officer will walk you through different loan options based on what you qualify for. Mortgage rates can vary between different loan products and programs. Even after you find a home you love, other things can have an impact too. For example: A mortgage rate buydown: This helps you get a lower mortgage rate, and by extension, a lower monthly payment, by paying an upfront cost. Sometimes a seller, builder, or another party may even offer to cover that cost themselves as an incentive for you to buy. Seller concessions : Sellers are allowed to pay buyer closing costs according to most loan program guidelines. Seller-paid closing costs can add up to thousands of dollars, which can free up some cash for you to increase your down payment, pay down debt, or make other financial adjustments to try to get a better rate. Your First Step? Getting Pre-Approved. If you want to know if your number could be higher or lower than the headlines on social, you need to talk to an expert. A simple conversation with a loan officer can help you determine when you’ll be ready to buy, how much you can borrow, and of course, what your real rate will be. Your lender may recommend a pre-qualification and pre-approval: Pre-qualification is a general estimate of what you might be able to borrow based on self-reported information. On the flip side, pre-approval is actually a conditional commitment from a lender based on verified information. Just know that, of the two, the pre-approval process gives you a more accurate picture of your options than pre-qualification. Bankrate gives a quick comparison so you can see why: 
September 23, 2026
Data centers probably weren't on your list of things to think about when buying or selling a home. School districts? Sure. How close you are to family? Absolutely. A large building full of computer servers down the road? Probably not. But that may be changing. Data centers are popping up in more communities across the country. And as they do, buyers and homeowners are starting to wonder what having one nearby could mean for everything from home values to utility bills. So, let's get into what the data actually says. Because there's a lot more nuance here than if they’re “good” or “bad.” Data Centers Are Showing Up in a Lot More ZIP Codes According to Realtor.com , back in 2015, only about a dozen ZIP codes had a large data center. But by the first half of 2026, that number had climbed to more than 100 – and it's projected to rise even further by the end of the year ( see graph below ):
September 23, 2026
Summer's winding down, and if you've been thinking about selling , you might be wondering if you missed your chance. Better to wait until next year or even next spring, right? Not so fast. About one in three of all home sales happen in the last four months of the year. Fall Is Busier than You Think Data from the National Association of Realtors (NAR) shows around a third of existing home sales happen in the final four months of the year. And that share has grown every year since 2023 ( see graph below ):
September 12, 2026
You've been waiting for something to change before you buy. It just might not be the thing you expected… While everyone’s paying attention to mortgage rates , only the savviest buyers know that the changing season can start tipping things in their favor. Because every fall, buyers tend to get more to choose from, better prices, and more room to negotiate. And that’s why Hannah Jones, Senior Economist at Realtor.com , says : “ We always see that the best time to buy window usually falls in the early fall around October. ” And that’s exactly why, if you've been waiting for a better moment to buy, this season may be worth a closer look – even with rates where they are. 1. There Are More Homes To Choose From One of the biggest frustrations buyers have had over the past few years has been a lack of choices. Fall tends to help with that. Based on seasonal trends, Realtor.com data shows there are typically more homes available for sale in September through November than during any other season of the year ( see graph below ): 
September 10, 2026
For most first-time buyers, the hardest part of buying a home is making the numbers work . You budget, you save, and the finish line still feels far away. But your salary is only half the equation. Where you live shapes what you can afford just as much. And if you can work remotely, you have an advantage a lot of buyers don't. You're not tied to living where the jobs are, so you can look where your money goes further. Where You Work Doesn’t Have To Dictate Where You Live Remote job openings are on the rise. According to FlexJobs, remote job postings climbed 22% from the quarter before. That’s the second quarter in a row of double-digit growth. More remote roles mean more people can choose a home base around the life they want to build. As Forbes puts it : “ Remote employees, freelancers, consultants, entrepreneurs, and business owners have the flexibility to choose a home base based on the life they want to build, whether that means more space, a lower cost of living, better access to nature, or simply somewhere new." And you can use that freedom to look somewhere more affordable . Your Paycheck Goes Much Further in Some States Your cost of living – what you spend on housing, groceries, utilities, and the rest of daily life – varies a lot from one state to the next. In some, according to data from Extra Space, it runs far enough below the national average to change what you can afford ( see map below ):
September 5, 2026
You're scrolling through listings on your phone and everything looks good until you see the price (or the estimated monthly payment). Then you close the app. Because even if you love the house, the numbers feel impossible. But here's the thing, they may not be. Nationally, there are more homes sitting on the market than there are people out there looking. And when sellers need buyers more than buyers need sellers , that shows up in the price. Lower asking prices. More price cuts. And homes priced for what buyers can actually afford – not what sellers hope someone might pay. And it may be enough to make buying more doable than you’d think. 4 Out of 10 Sellers Are Cutting Their Price One of the clearest signs sellers are adjusting? Price cuts. HousingWire Data shows more than 40% of sellers are dropping this price. That’s just slightly behind the volume we saw last year ( see graph below ): 
September 3, 2026
Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home. Maybe you've caught the buzz and wondered whether that money could get you into a home faster, especially with affordability as tough as it is. Here’s what you need to remember. Pulling from your retirement savings is a big decision, so take time to weigh all your options first and be sure to talk with a financial expert before you do anything. A lot of buyers ask if they can use retirement money for a down payment. The short answer is: sometimes. The better answer is: there are a few different ways to do it, and they are not all the same. 1. 401(k) loan (borrowing from yourself) If your employer plan allows it, this is usually the cleanest option. You borrow from your own 401(k), typically up to 50% of your vested balance or $50,000, whichever is less. There is generally no income tax and no 10% penalty as long as you repay it on schedule. The interest you pay goes back into your own account. Two things to watch: If you leave your job before the loan is paid off, the remaining balance can become taxable. Some plans allow a longer payoff period when the loan is used to buy a primary residence. 2. 401(k) hardship withdrawal Some plans allow a withdrawal for costs tied to buying a principal residence. This is not a loan. You do not pay it back. You will usually owe income tax, and if you’re under 59½ the 10% penalty often still applies. There is no special first-time homebuyer penalty exception for 401(k)s. 3. IRA first-time homebuyer exception IRAs work differently. You generally cannot take a loan from an IRA, but first-time buyers (no principal residence in the last two years) may withdraw up to $10,000 penalty-free. A married couple can often use $10,000 each. Traditional IRA withdrawals are still taxable. Roth IRA contributions can usually come out tax- and penalty-free; earnings have extra rules Why Dipping into a 401(k) Can Be Tempting Data from Empower shows many Americans have built up considerable retirement savings. The median 401(k) amount for anyone in their 40s-60s is six figures (see graph below  ):
Show More