Expert Forecasts Point to Affordability Improving in 2026

January 17, 2026

Wondering what to expect from the housing market in 2026? You’re not the only one. For the past few years, affordability has been the biggest barrier standing between most people and their next move. And a lot of buyers and sellers have been holding their breath waiting for things to get better. The good news? It’s finally happening.


In 2025, affordability was the best it’s been in 3 years. And experts agree the momentum will keep going in 2026. And that’s based on their analysis of the key factors shaping the housing market in the year ahead: mortgage rates, inventory, and home prices.


Lower Mortgage Rates Are Already Here


Mortgage rates have already come down from their peak. By some counts, they dropped by almost a full percentage point over the course of the last year. And that’s a big deal, even if it doesn’t sound like it. But how low will they go? And should you wait for them to come down more? Here’s your answer. 


Forecasts suggest they’ll stay pretty much where they are now and hover in the low 6% range throughout 2026 (see graph below):
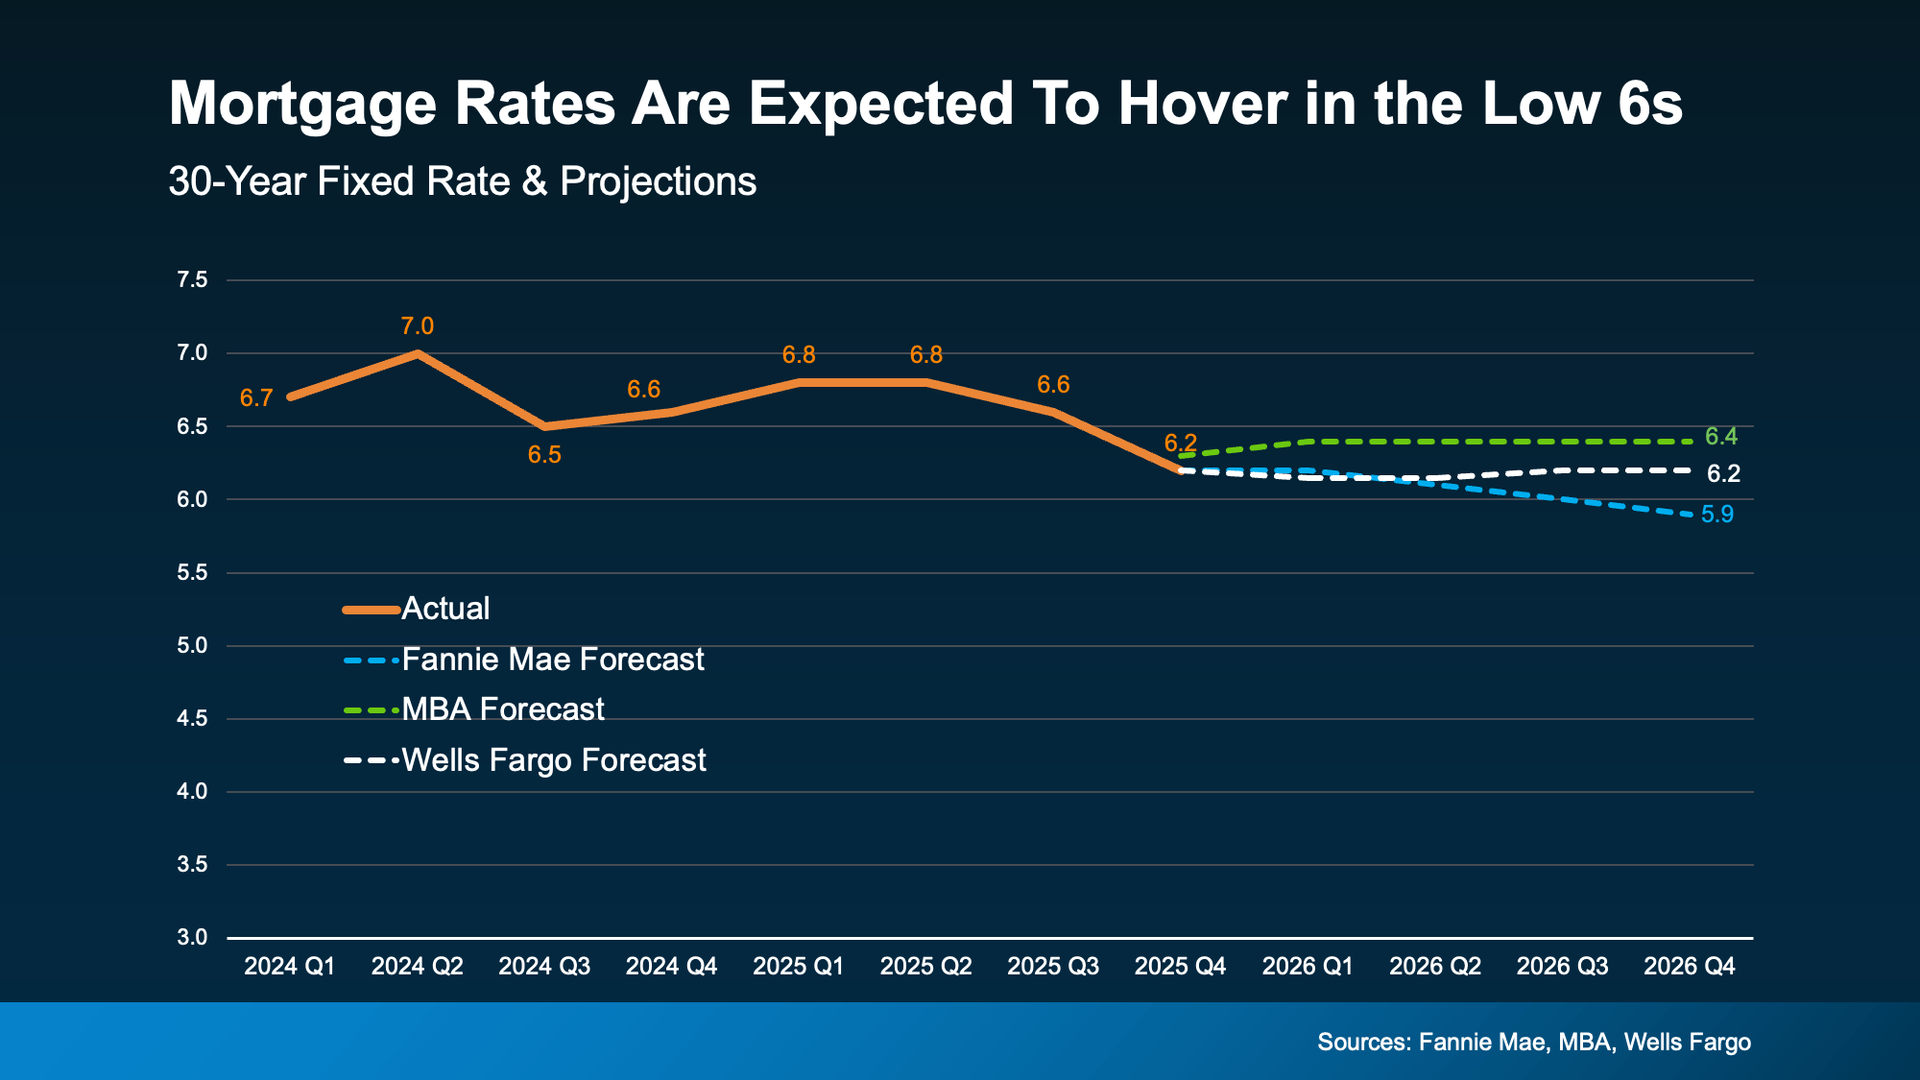
Where they go from here really depends on what happens with the economy, the job market, and any changes in monetary policy the Fed makes in the year ahead. The important thing is, they’re already lower than they were just one year ago and that’s ideal if you’re planning a 2026 move.


  • For buyers: A lower rate reduces monthly payments and increases buying power. And, that combo helps more people qualify for homes that previously felt just out of reach.
  • For sellers: It may be time to accept that rates in the 6s are the new normal. And if you need to move, it’s doable, especially with your equity.


Even More Options Are on the Way


In 2025, the number of homes for sale improved by about 15%. As inventory rose, buyers regained things they hadn’t had in years: options, time to consider those options, and negotiating leverage. That helped restore more balance to the housing market.


Not to mention, the inventory gains are a big piece of what’s helped price growth slow down – which in turn improves affordability.


While the inventory gains this year aren’t expected to be as steep, experts at Realtor.com say the supply of homes for sale should grow by another 8.9% this year.


  • For buyers: That means even more choice and more negotiating power.
  • For sellers: Pricing your house right will be essential to draw in buyers.


Home Price Growth Is Slowing to a More Sustainable Pace


With more homes for sale, there isn’t as much upward pressure on prices right now. And we’ve seen that shake out over the past year. Even so, the overwhelming majority of experts say, nationally, prices will continue rising in the year ahead – just at a slower pace. On average, they say prices will rise by 1.6% in 2026 (see graph below):
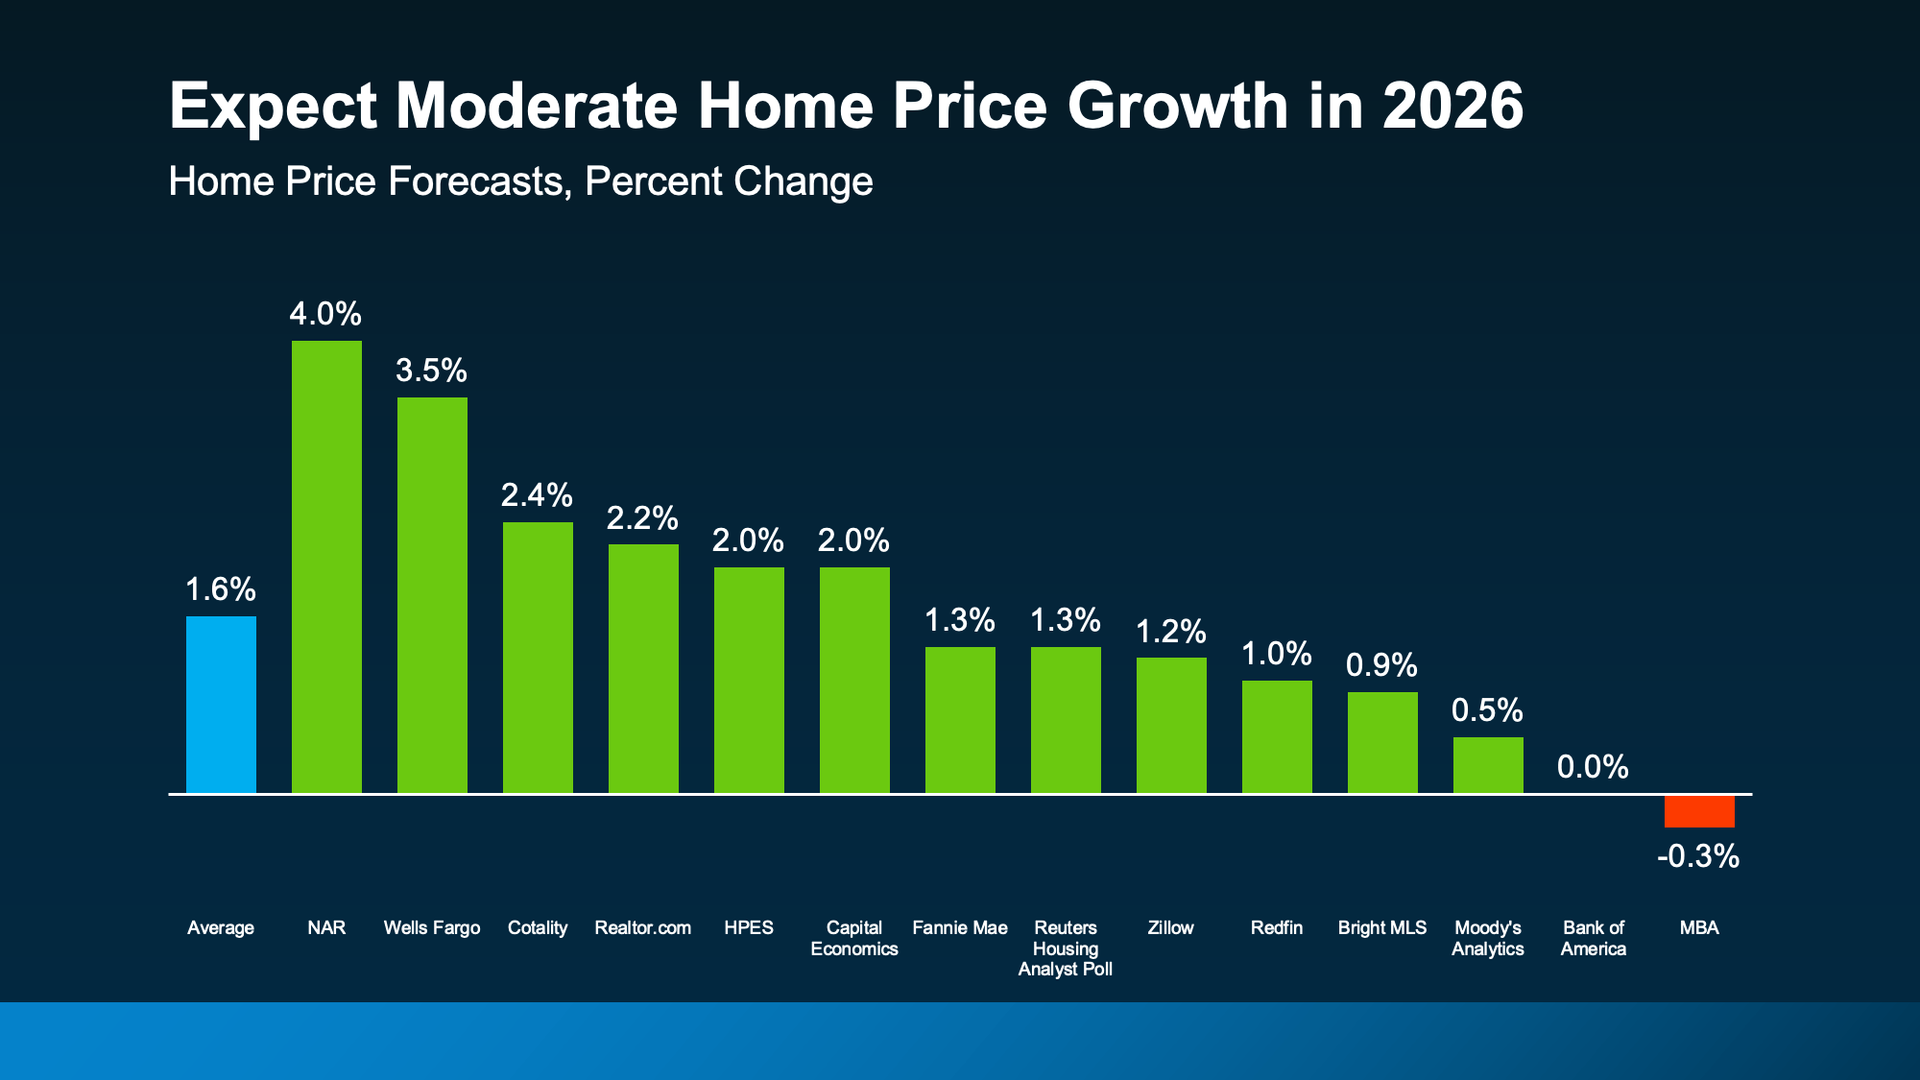
And that's reassuring if you've been fed content on social media saying prices are going to come crashing down. But here’s what you need to remember most about this. It’s going to vary a lot by area.


So, lean on a local agent for the latest on what’s happening where you are. Some markets will see prices rise more than this. Others may see prices come down slightly. It really all depends on conditions in your local market


But overall, prices will continue to rise at the national level. And that’s good for the market as a whole. As Realtor.com explains:


“ For homebuyers and sellers, the shift signals a more balanced market —one where price growth steadies, rate relief offers breathing room, and negotiating power tilts subtly toward buyers.”


  • For buyers: Expect more moderate price growth, not the sudden and intense spikes just a few short years ago. That gives you fewer surprises and more predictability, which makes budgeting a whole lot easier.
  • For sellers: This slower price growth restores balance without putting your equity at risk. And that’s a win. 


More Homes Will Sell 


All of this adds up to a better affordability equation in 2026. And that’s exactly why experts are saying we should see more homes sell (and more people buy) this year.
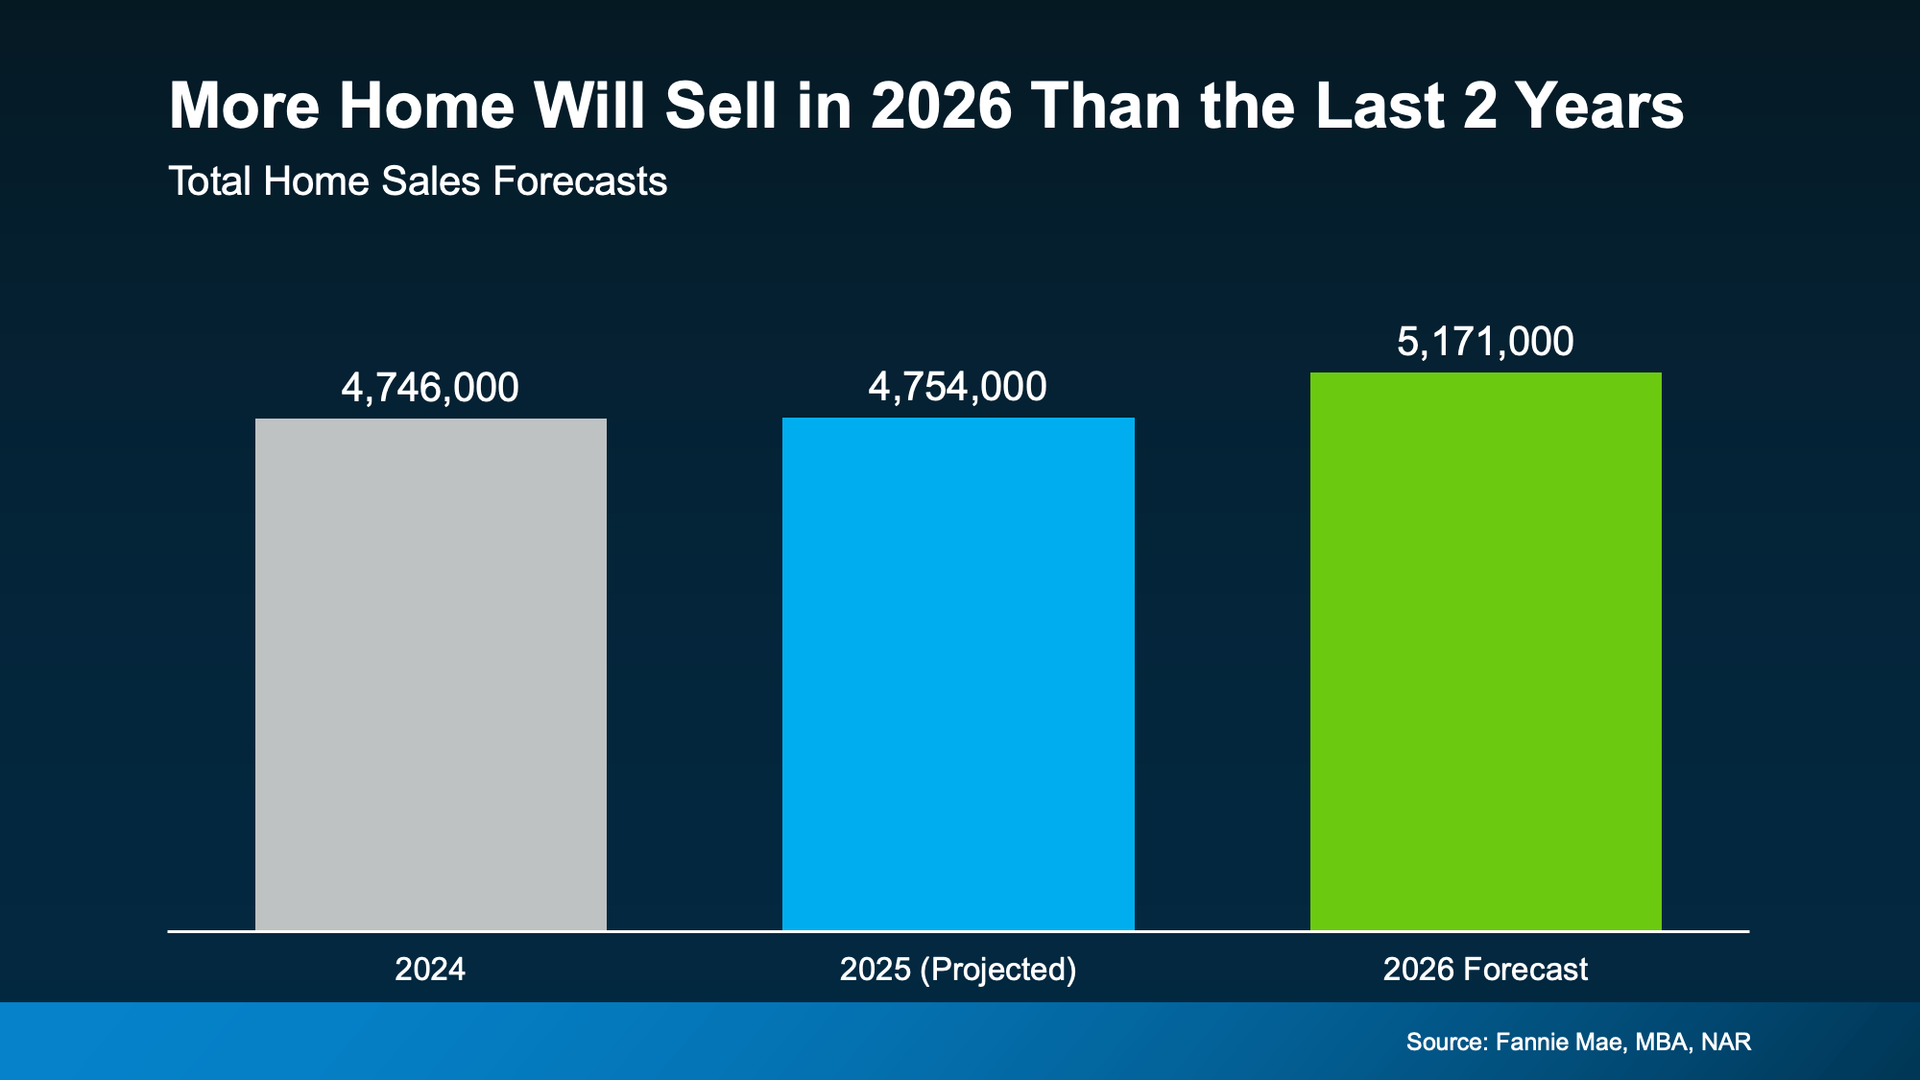
As Mischa Fisher, Chief Economist at Zillow, says:


“Buyers are benefiting from more inventory and improved affordability, while sellers are seeing price stability and more consistent demand. Each group should have a bit more breathing room in 2026 .”


The bottom line is, more people are finally going to be able to make their move this year. So, the question is: will you be one of them? The market is giving you an opportunity you haven’t had in a while. Maybe it’s time to take advantage of it.


Bottom Line


Affordability won't change suddenly overnight in Granite Bay And Eldorado Hills, or anywhere in the Sacramento valley. However , with several key trends working together, it should slowly and steadily improve in the months ahead.


That’s exactly why, in 2026, you should see a market with more balance, more predictability, and more breathing room than you’ve had in years.


Want more information about the opportunities unlocking in our local market?


Let’s chat.
September 23, 2026
Data centers probably weren't on your list of things to think about when buying or selling a home. School districts? Sure. How close you are to family? Absolutely. A large building full of computer servers down the road? Probably not. But that may be changing. Data centers are popping up in more communities across the country. And as they do, buyers and homeowners are starting to wonder what having one nearby could mean for everything from home values to utility bills. So, let's get into what the data actually says. Because there's a lot more nuance here than if they’re “good” or “bad.” Data Centers Are Showing Up in a Lot More ZIP Codes According to Realtor.com , back in 2015, only about a dozen ZIP codes had a large data center. But by the first half of 2026, that number had climbed to more than 100 – and it's projected to rise even further by the end of the year ( see graph below ):
September 23, 2026
Summer's winding down, and if you've been thinking about selling , you might be wondering if you missed your chance. Better to wait until next year or even next spring, right? Not so fast. About one in three of all home sales happen in the last four months of the year. Fall Is Busier than You Think Data from the National Association of Realtors (NAR) shows around a third of existing home sales happen in the final four months of the year. And that share has grown every year since 2023 ( see graph below ):
September 12, 2026
You've been waiting for something to change before you buy. It just might not be the thing you expected… While everyone’s paying attention to mortgage rates , only the savviest buyers know that the changing season can start tipping things in their favor. Because every fall, buyers tend to get more to choose from, better prices, and more room to negotiate. And that’s why Hannah Jones, Senior Economist at Realtor.com , says : “ We always see that the best time to buy window usually falls in the early fall around October. ” And that’s exactly why, if you've been waiting for a better moment to buy, this season may be worth a closer look – even with rates where they are. 1. There Are More Homes To Choose From One of the biggest frustrations buyers have had over the past few years has been a lack of choices. Fall tends to help with that. Based on seasonal trends, Realtor.com data shows there are typically more homes available for sale in September through November than during any other season of the year ( see graph below ): 
September 10, 2026
For most first-time buyers, the hardest part of buying a home is making the numbers work . You budget, you save, and the finish line still feels far away. But your salary is only half the equation. Where you live shapes what you can afford just as much. And if you can work remotely, you have an advantage a lot of buyers don't. You're not tied to living where the jobs are, so you can look where your money goes further. Where You Work Doesn’t Have To Dictate Where You Live Remote job openings are on the rise. According to FlexJobs, remote job postings climbed 22% from the quarter before. That’s the second quarter in a row of double-digit growth. More remote roles mean more people can choose a home base around the life they want to build. As Forbes puts it : “ Remote employees, freelancers, consultants, entrepreneurs, and business owners have the flexibility to choose a home base based on the life they want to build, whether that means more space, a lower cost of living, better access to nature, or simply somewhere new." And you can use that freedom to look somewhere more affordable . Your Paycheck Goes Much Further in Some States Your cost of living – what you spend on housing, groceries, utilities, and the rest of daily life – varies a lot from one state to the next. In some, according to data from Extra Space, it runs far enough below the national average to change what you can afford ( see map below ):
September 5, 2026
You're scrolling through listings on your phone and everything looks good until you see the price (or the estimated monthly payment). Then you close the app. Because even if you love the house, the numbers feel impossible. But here's the thing, they may not be. Nationally, there are more homes sitting on the market than there are people out there looking. And when sellers need buyers more than buyers need sellers , that shows up in the price. Lower asking prices. More price cuts. And homes priced for what buyers can actually afford – not what sellers hope someone might pay. And it may be enough to make buying more doable than you’d think. 4 Out of 10 Sellers Are Cutting Their Price One of the clearest signs sellers are adjusting? Price cuts. HousingWire Data shows more than 40% of sellers are dropping this price. That’s just slightly behind the volume we saw last year ( see graph below ): 
September 3, 2026
Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home. Maybe you've caught the buzz and wondered whether that money could get you into a home faster, especially with affordability as tough as it is. Here’s what you need to remember. Pulling from your retirement savings is a big decision, so take time to weigh all your options first and be sure to talk with a financial expert before you do anything. A lot of buyers ask if they can use retirement money for a down payment. The short answer is: sometimes. The better answer is: there are a few different ways to do it, and they are not all the same. 1. 401(k) loan (borrowing from yourself) If your employer plan allows it, this is usually the cleanest option. You borrow from your own 401(k), typically up to 50% of your vested balance or $50,000, whichever is less. There is generally no income tax and no 10% penalty as long as you repay it on schedule. The interest you pay goes back into your own account. Two things to watch: If you leave your job before the loan is paid off, the remaining balance can become taxable. Some plans allow a longer payoff period when the loan is used to buy a primary residence. 2. 401(k) hardship withdrawal Some plans allow a withdrawal for costs tied to buying a principal residence. This is not a loan. You do not pay it back. You will usually owe income tax, and if you’re under 59½ the 10% penalty often still applies. There is no special first-time homebuyer penalty exception for 401(k)s. 3. IRA first-time homebuyer exception IRAs work differently. You generally cannot take a loan from an IRA, but first-time buyers (no principal residence in the last two years) may withdraw up to $10,000 penalty-free. A married couple can often use $10,000 each. Traditional IRA withdrawals are still taxable. Roth IRA contributions can usually come out tax- and penalty-free; earnings have extra rules Why Dipping into a 401(k) Can Be Tempting Data from Empower shows many Americans have built up considerable retirement savings. The median 401(k) amount for anyone in their 40s-60s is six figures (see graph below  ):
August 29, 2026
When's the last time someone told you what your house is worth? Not what some online valuation tool guessed. Not what your neighbor's house sold for. What yours is actually worth right now . For a lot of homeowners, it's been years. And if you've been thinking about moving , but higher home prices or mortgage rates have made you hesitate, here’s why it’s time to take a second look at that number. Your House May Be Worth More Than You Think Home values have climbed significantly over the past 5-10 years. And even though today's market is more balanced , homeowners are building wealth every day just by owning their homes. That’s how equity works. As home values rise, and as you make your monthly payments, your equity grows. And it adds up fast. According to Cotality , the typical homeowner with a mortgage now has $310,500 in equity. That's not a small number. It’s six figures. And that’s only the national average. In many states, homeowners have built even more equity than that. Take a look at the map below and see where your state stands. The darker the blue, the more equity the typical homeowner has there (see map below): 
August 26, 2026
Few things are as rattling as the thought of your home sale falling through at the last minute, right before closing. All that waiting, all that progress, out the window. But if you’re getting ready to sell, here’s what you should know. Even in today’s market, it rarely comes to that. Buyers who are moving at today’s rates and prices are generally moving because of some big life change. That means they’re motivated, and eager to get all the way to the closing table. According to the latest data from Redfin , only about 1 in 7 pending sales are falling through . Meaning the vast majority make it all the way to closing. And the single biggest thing that puts a deal at risk is the one you have the most power to prevent. It just takes a little smart planning before your house hits the market. Why Some Deals Fall Apart Before Closing A Redfin survey sheds light on the most common things that trip up a sale ( see visual below ):
August 22, 2026
Ask around and almost every homebuyer out there wants to know if there’s a way to get a better deal . And just about every seller wants to know if they'll still get top dollar . The interesting thing is... both can be right at the exact same time . It just depends on where you live. That's because today's housing market isn't moving in one direction anymore. Some markets clearly favor buyers. Others still favor sellers. But most are sitting somewhere in the middle. And knowing which market you're actually in can completely change the strategy you use to buy or sell (and what expectations you should have). Let’s break it down. One Number Tells You Who's Got Leverage So how do you know which market you're in? There's one number that tells the story faster than anything else: the months' supply of homes for sale. It's the clearest signal of who's got leverage – and what strategy you'll need. Think of it like this. Imagine no additional homes were listed starting today. Months' supply tells us how long it would take to sell everything that's currently on the market based on today’s demand. Generally speaking, if months’ supply is: Fewer than 4 months: Sellers usually have the advantage. 4 to 6 months: Buyers and sellers are on more equal footing. More than 6 months: Buyers can usually negotiate for a better deal. Right now, the National Association of Realtors (NAR) data says that number is 4.6 and that puts the overall market back in balanced territory ( see graph below ):
August 20, 2026
That spare room on the main floor. The finished basement with a kitchenette and its own entrance. The bonus room you've been using for storage. To you, it's extra space. But to a growing pool of buyers, it's the reason they'd pick your house . Here’s why. Multi-generational homebuying is on the rise. Millions of Families Are Living Multi-Generationally The number of multi-generational households is climbing. That’s when 3 or more generations live under one roof. And data shows those households grew from 3.2 million to almost 4 million between 2014 and 2024, according to Realtor.com . And each year, more people are shopping for a larger home that fits their combined needs. While the appetite for this type of house is rising across the board, data from USAFacts shows multi-generational living is more common in some states than others. The darker the state in the map below, the more common it is in that area ( see map below ): 
Show More
September 23, 2026
Data centers probably weren't on your list of things to think about when buying or selling a home. School districts? Sure. How close you are to family? Absolutely. A large building full of computer servers down the road? Probably not. But that may be changing. Data centers are popping up in more communities across the country. And as they do, buyers and homeowners are starting to wonder what having one nearby could mean for everything from home values to utility bills. So, let's get into what the data actually says. Because there's a lot more nuance here than if they’re “good” or “bad.” Data Centers Are Showing Up in a Lot More ZIP Codes According to Realtor.com , back in 2015, only about a dozen ZIP codes had a large data center. But by the first half of 2026, that number had climbed to more than 100 – and it's projected to rise even further by the end of the year ( see graph below ):
September 23, 2026
Summer's winding down, and if you've been thinking about selling , you might be wondering if you missed your chance. Better to wait until next year or even next spring, right? Not so fast. About one in three of all home sales happen in the last four months of the year. Fall Is Busier than You Think Data from the National Association of Realtors (NAR) shows around a third of existing home sales happen in the final four months of the year. And that share has grown every year since 2023 ( see graph below ):
September 12, 2026
You've been waiting for something to change before you buy. It just might not be the thing you expected… While everyone’s paying attention to mortgage rates , only the savviest buyers know that the changing season can start tipping things in their favor. Because every fall, buyers tend to get more to choose from, better prices, and more room to negotiate. And that’s why Hannah Jones, Senior Economist at Realtor.com , says : “ We always see that the best time to buy window usually falls in the early fall around October. ” And that’s exactly why, if you've been waiting for a better moment to buy, this season may be worth a closer look – even with rates where they are. 1. There Are More Homes To Choose From One of the biggest frustrations buyers have had over the past few years has been a lack of choices. Fall tends to help with that. Based on seasonal trends, Realtor.com data shows there are typically more homes available for sale in September through November than during any other season of the year ( see graph below ): 
September 10, 2026
For most first-time buyers, the hardest part of buying a home is making the numbers work . You budget, you save, and the finish line still feels far away. But your salary is only half the equation. Where you live shapes what you can afford just as much. And if you can work remotely, you have an advantage a lot of buyers don't. You're not tied to living where the jobs are, so you can look where your money goes further. Where You Work Doesn’t Have To Dictate Where You Live Remote job openings are on the rise. According to FlexJobs, remote job postings climbed 22% from the quarter before. That’s the second quarter in a row of double-digit growth. More remote roles mean more people can choose a home base around the life they want to build. As Forbes puts it : “ Remote employees, freelancers, consultants, entrepreneurs, and business owners have the flexibility to choose a home base based on the life they want to build, whether that means more space, a lower cost of living, better access to nature, or simply somewhere new." And you can use that freedom to look somewhere more affordable . Your Paycheck Goes Much Further in Some States Your cost of living – what you spend on housing, groceries, utilities, and the rest of daily life – varies a lot from one state to the next. In some, according to data from Extra Space, it runs far enough below the national average to change what you can afford ( see map below ):
September 5, 2026
You're scrolling through listings on your phone and everything looks good until you see the price (or the estimated monthly payment). Then you close the app. Because even if you love the house, the numbers feel impossible. But here's the thing, they may not be. Nationally, there are more homes sitting on the market than there are people out there looking. And when sellers need buyers more than buyers need sellers , that shows up in the price. Lower asking prices. More price cuts. And homes priced for what buyers can actually afford – not what sellers hope someone might pay. And it may be enough to make buying more doable than you’d think. 4 Out of 10 Sellers Are Cutting Their Price One of the clearest signs sellers are adjusting? Price cuts. HousingWire Data shows more than 40% of sellers are dropping this price. That’s just slightly behind the volume we saw last year ( see graph below ): 
September 3, 2026
Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home. Maybe you've caught the buzz and wondered whether that money could get you into a home faster, especially with affordability as tough as it is. Here’s what you need to remember. Pulling from your retirement savings is a big decision, so take time to weigh all your options first and be sure to talk with a financial expert before you do anything. A lot of buyers ask if they can use retirement money for a down payment. The short answer is: sometimes. The better answer is: there are a few different ways to do it, and they are not all the same. 1. 401(k) loan (borrowing from yourself) If your employer plan allows it, this is usually the cleanest option. You borrow from your own 401(k), typically up to 50% of your vested balance or $50,000, whichever is less. There is generally no income tax and no 10% penalty as long as you repay it on schedule. The interest you pay goes back into your own account. Two things to watch: If you leave your job before the loan is paid off, the remaining balance can become taxable. Some plans allow a longer payoff period when the loan is used to buy a primary residence. 2. 401(k) hardship withdrawal Some plans allow a withdrawal for costs tied to buying a principal residence. This is not a loan. You do not pay it back. You will usually owe income tax, and if you’re under 59½ the 10% penalty often still applies. There is no special first-time homebuyer penalty exception for 401(k)s. 3. IRA first-time homebuyer exception IRAs work differently. You generally cannot take a loan from an IRA, but first-time buyers (no principal residence in the last two years) may withdraw up to $10,000 penalty-free. A married couple can often use $10,000 each. Traditional IRA withdrawals are still taxable. Roth IRA contributions can usually come out tax- and penalty-free; earnings have extra rules Why Dipping into a 401(k) Can Be Tempting Data from Empower shows many Americans have built up considerable retirement savings. The median 401(k) amount for anyone in their 40s-60s is six figures (see graph below  ):
August 29, 2026
When's the last time someone told you what your house is worth? Not what some online valuation tool guessed. Not what your neighbor's house sold for. What yours is actually worth right now . For a lot of homeowners, it's been years. And if you've been thinking about moving , but higher home prices or mortgage rates have made you hesitate, here’s why it’s time to take a second look at that number. Your House May Be Worth More Than You Think Home values have climbed significantly over the past 5-10 years. And even though today's market is more balanced , homeowners are building wealth every day just by owning their homes. That’s how equity works. As home values rise, and as you make your monthly payments, your equity grows. And it adds up fast. According to Cotality , the typical homeowner with a mortgage now has $310,500 in equity. That's not a small number. It’s six figures. And that’s only the national average. In many states, homeowners have built even more equity than that. Take a look at the map below and see where your state stands. The darker the blue, the more equity the typical homeowner has there (see map below): 
August 26, 2026
Few things are as rattling as the thought of your home sale falling through at the last minute, right before closing. All that waiting, all that progress, out the window. But if you’re getting ready to sell, here’s what you should know. Even in today’s market, it rarely comes to that. Buyers who are moving at today’s rates and prices are generally moving because of some big life change. That means they’re motivated, and eager to get all the way to the closing table. According to the latest data from Redfin , only about 1 in 7 pending sales are falling through . Meaning the vast majority make it all the way to closing. And the single biggest thing that puts a deal at risk is the one you have the most power to prevent. It just takes a little smart planning before your house hits the market. Why Some Deals Fall Apart Before Closing A Redfin survey sheds light on the most common things that trip up a sale ( see visual below ):
August 22, 2026
Ask around and almost every homebuyer out there wants to know if there’s a way to get a better deal . And just about every seller wants to know if they'll still get top dollar . The interesting thing is... both can be right at the exact same time . It just depends on where you live. That's because today's housing market isn't moving in one direction anymore. Some markets clearly favor buyers. Others still favor sellers. But most are sitting somewhere in the middle. And knowing which market you're actually in can completely change the strategy you use to buy or sell (and what expectations you should have). Let’s break it down. One Number Tells You Who's Got Leverage So how do you know which market you're in? There's one number that tells the story faster than anything else: the months' supply of homes for sale. It's the clearest signal of who's got leverage – and what strategy you'll need. Think of it like this. Imagine no additional homes were listed starting today. Months' supply tells us how long it would take to sell everything that's currently on the market based on today’s demand. Generally speaking, if months’ supply is: Fewer than 4 months: Sellers usually have the advantage. 4 to 6 months: Buyers and sellers are on more equal footing. More than 6 months: Buyers can usually negotiate for a better deal. Right now, the National Association of Realtors (NAR) data says that number is 4.6 and that puts the overall market back in balanced territory ( see graph below ):
August 20, 2026
That spare room on the main floor. The finished basement with a kitchenette and its own entrance. The bonus room you've been using for storage. To you, it's extra space. But to a growing pool of buyers, it's the reason they'd pick your house . Here’s why. Multi-generational homebuying is on the rise. Millions of Families Are Living Multi-Generationally The number of multi-generational households is climbing. That’s when 3 or more generations live under one roof. And data shows those households grew from 3.2 million to almost 4 million between 2014 and 2024, according to Realtor.com . And each year, more people are shopping for a larger home that fits their combined needs. While the appetite for this type of house is rising across the board, data from USAFacts shows multi-generational living is more common in some states than others. The darker the state in the map below, the more common it is in that area ( see map below ): 
Show More