Renting vs. Buying: The Net Worth Gap You Need To See
November 15, 2024

Trying to decide between renting or buying a home? One key factor that could help you choose is just how much homeownership can grow your net worth.


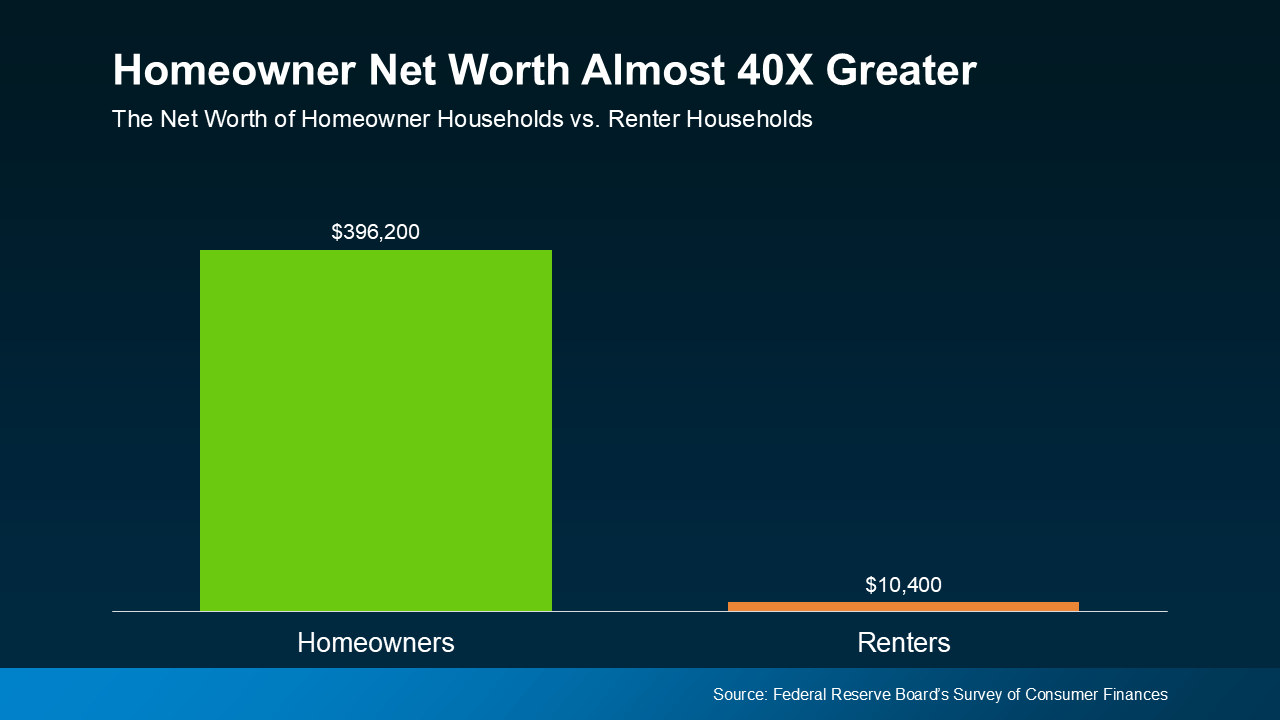
Every three years, the Federal Reserve Board shares a report called the Survey of Consumer Finances (SCF). It shows how much wealth homeowners and renters have – and the difference is significant.


On average, a homeowner’s net worth is nearly 40 times higher than a renter’s. Check out the graph below to see the difference for yourself:
Why Homeowner Wealth Is So High


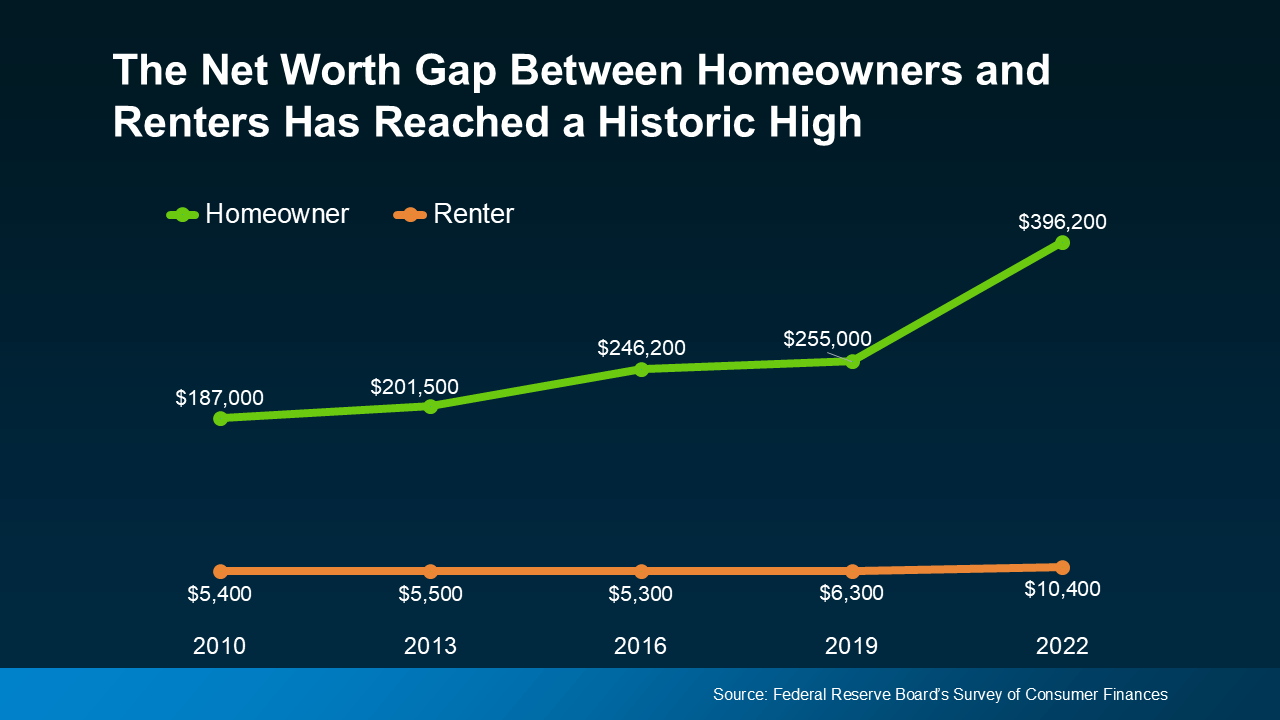
In the previous version of that report, the average homeowner’s net worth was about $255,000, while the average renter’s was just $6,300. That’s still a big gap. But in the most recent update, the spread got even bigger as homeowner wealth grew even more (see graph below):
As the SCF report says:

        “. . . the 2019-2022 growth in median net worth was the largest three-year increase over the history of             the modern SCF, more than double the next-largest one on record.”


One big reason why homeowner wealth shot up is home equity.


Equity is the difference between your home’s value and what you owe on your mortgage. You gain equity by paying down your mortgage and when your home’s value goes up.


Over the past few years, home prices have gone up a lot. That’s because there weren’t enough available homes for all the people who wanted one. This supply-demand imbalance pushed home prices up – and that translated into faster equity gains and even more net worth for homeowners.


If you’re still torn between whether to rent or buy, here’s what you should know. While inventory has grown this year, in most places, there’s still not enough to go around. That’s why expert forecasts show prices are expected to go up again next year nationally. It’ll just be at a more moderate pace.


While that’s not the sky-high appreciation we saw during the pandemic, it still means potential equity gains for you if you buy now. As Ksenia Potapov, Economist at First American, explains:


        “Despite the risk of volatility in the housing market, homeownership remains an important driver of                  wealth accumulation and the largest source of total wealth among most households .”


But prices and inventory are going to vary by area. So, lean on me as your local real estate agent in Granite Bay. Roseville, Rocklin, Sacramento, or Eldorado Hills. I will be able to give you the local trends and speak to the other financial and lifestyle benefits that come with owning a home. That crucial information will help you decide the best move for you right now. As Bankrate explains:


“Deciding between renting and buying a home isn’t just about cost — the decision also involves long-term financial strategies and personal circumstances.  If you’re on the fence about which is right for you, it may be helpful to speak with a local real estate agent who knows your market well. An experienced agent can help you weigh your options and make a more informed decision. ”


Bottom Line


If you’re not sure if you should rent or buy a house in Roseville or Granite Bay, give me a call so we can try to make it happen. If you can make the numbers work monthly, owning a home can really grow your wealth over time.


If homeownership feels out of reach, let’s connect so we can explore programs that may make buying possible. 
October 24, 2026
What's the biggest payment you make every month? If you’re a renter , it's probably your rent. But did you know that you can pay your rent on time, every time, for years, and it may never show up in your credit history? It's pretty frustrating, especially if you'd like to buy a home someday and you’re trying to build your credit. The good thing is that’s changing right now. Here’s what you need to know and why it could open a door you thought was closed. The Problem for Would-Be Buyers You’re not the only one frustrated. According to Zillow, nearly a third of applicants (32.88%) get denied a mortgage due to insufficient credit history - not missed payments or too much debt. Just not enough credit history for a lender to say "yes." It’s the most common hurdle would-be buyers have. As Zillow explains: "Nearly one-third of mortgage applicants are denied a loan because of insufficient credit history , making it the most common reason for a denial .” 
October 21, 2026
When you picture buying your first home , chances are you’re imagining a traditional single-family house with its own yard, maybe a garage, and little extra room to grow. But with affordability still tight, getting everything on that list right away may come with a higher price tag than you’re comfortable with right now. So, if you’re running the numbers and buying a house like that feels like a stretch, there may be another way in. A condo. Because in a lot of markets, condos come with a significantly lower price tag. And that could make them a smart way to get your foot in the door. Condos Can Cost Less Than You Think According to a recent study by Zillow: “ Condos are the most commonly affordable home type in virtually every metro. At the starter level, the savings can be pretty significant. Nationally, starter condos average $197,468 — that’s about 6% less than the typical starter home. ” And depending on where you live, the difference can be much bigger. Zillow identified metro areas where typical starter condos are priced significantly below the estimated home price a median-income household could afford. Here are the top 10 according to that research ( see chart below ). In Houston, the gap is at its widest. There, a typical starter condo was valued at about $85,600 – 72% below the price considered affordable based on the area's median household income. 
October 17, 2026
You've spent years making your house feel like home, celebrating milestones, making each room your own, and turning neighbors into friends. As you look ahead to the next chapter of your life, it's natural to wonder if this is still the place you want to spend it. Whether you're leaning toward staying in your house as you get older or moving to a 55+ community, the goal is the same: a home that fits the life you want, with more time for the people and things you love. So, here's what to consider before you decide. What It Can Take To Stay Put Wanting to stay in a house you love and are familiar with makes sense. But most houses need at least some updates to make aging in place easier. In fact, the Joint Center for Housing Studies of Harvard University (JCHS) finds that fewer than 4% of homes have the basics, like single-floor living, no-step entries, and wide hallways and doorways (see graph below): 
October 13, 2026
With everything going on, it’s understandable if you’re wondering if you’d regret buying right now. Everyday expenses cost more. Mortgage rates are higher than you’d like. And when the economy feels uncertain, taking on a mortgage can feel like a much bigger leap. But here’s some perspective that may help… Most people who already made that leap would do it again. According to a recent survey from NerdWallet, the vast majority of recent buyers (74%) were glad they bought their current home. Only a very small 3% of people regret it: 
October 10, 2026
Higher mortgage rates don't just affect buyers. They can change what it takes to sell your house, too. That's because today's buyers are paying close attention to affordability. And when rates rise, even a relatively small change can make a noticeable difference in their monthly payment. So, they're looking for ways to make the numbers work. And in some markets, new construction is giving them exactly that. If you're planning to sell , that doesn't mean you can't compete. But it does mean you need to understand what builders are doing to win over buyers – and what options you have, too. Builders Are Competing on the Monthly Payment New construction has something interesting going for it right now. While existing-home sales (homes that have previously been lived in, resale homes) continue to sell, the dated, or not updated ones tend to struggle under the weight of higher mortgage rates, new-home sales are holding up a bit better. Buyers in this market are very picky and don't over pay for a house that needs work. In a recent interview , Logan Mohtashami, Chief Economist at HousingWire explains new-home sales are at an 8-month high and are now running around 2019 levels . On the flip side, existing home sales are lagging behind and fall about 1 million home sales short of 2019 levels. One big reason builders have been able to navigate higher rates differently is incentives. According to Realtor.com , nearly 1 in 5 (18.8%) newly built homes come with some kind of buyer incentive advertised up front, here in Placer and Sacramento county I have seen 100% of the builders are offering some kind of incentives to the buyers of the standing inventory. 
October 6, 2026
For a lot of first-time buyers, owning a home can feel perpetually a few years out of reach. Saving for a down payment takes time, and each year you spend renting can make owning feel further off. But buying your first home doesn’t have to happen to feel like a far away goal. Two choices you control can bring your first home years closer, even with affordability as tight as it is right now. How Long Buying Really Takes First, one quick definition. "Breaking even" is the point where owning has cost you about the same as renting would have over the same period. And after that point, owning starts to cost less than renting. Kara Ng, Senior Economist at Zillow, puts it this way: "Buyers should think about not just when they can afford to buy, but how long they'd need to stay before owning makes more financial sense than renting." So how long does reaching that point usually take? And what are the shortcuts? Let’s do the math. According to Zillow, it usually takes about 8.5 years to save for a 20% down payment, then roughly 6.2 more years before owning costs the same as renting. Together, that's just under 15 years. But that math relies on two assumptions: that you're buying a mid-priced home, and that you're putting 20% down. Change either one and your timeline gets shorter. Change both and it can shrink fast. It also varies widely by market, since local prices and rents are different depending on where you live. A Starter Home Can Get You There Twice as Fast A starter home usually means a home in the lower third of local prices. They’re often condos , townhomes, or single-family homes a little smaller or older than others in the area. Choosing one over a mid-priced home can cut your wait down by a lot. And while that might sound obvious, you may not realize just how much it shortens your timeline. Because if you’re buying a more affordable home, you don’t have to save up as much or as long. Zillow found that nationwide, a starter home takes half the time – about 7.2 years – to save for and come out ahead on, compared with renting (see graph below): 
October 3, 2026
Price cuts are turning up everywhere right now, and they read very differently depending on which side of the deal you’re on. Sellers tend to worry a cut means walking away with less than they hoped. Sometimes that’s true, but more often it just means the market moved faster than the listing did. Buyers , for their part, often assume a cut means something’s wrong with the house. Most of the time, that’s not it. This is what's actually driving all those price cuts, and why it matters no matter which side of the deal you're on. 42% of Homes for Sale Are Now Carrying a Price Cut According to HousingWire Data , the share of sellers cutting their asking price has climbed every month for 7 straight months (see chart below):
September 29, 2026
You may have seen the headlines saying mortgage rates have climbed to the highest point since January 2025. And if that's left you reluctant to buy a home, here's what you need to remember… That's not necessarily the number you'd get. It's a common misconception that the rate you see in the headlines is the same one you'd get when you buy. The truth is, mortgage rates shift often, and the rate you actually end up with can vary a lot from what you may see or hear about. What Determines Your Real Rate? Advertised rates and “real rates” aren’t always the same. That’s because real rates are based on your specific situation, which includes your overall finances and goals. The rates you see in the headlines can’t possibly reflect that. That’s why only a lender can tell you what your real rate will be. To figure out your unique number, they’ll look at: Your credit score : Your credit score includes your payment history (if you’ve made late payments – and how often), credit utilization (are your accounts maxed out, or do you have available credit?), and the length of your credit history (how long have your accounts been open?). For example, someone with an exceptional credit score may qualify for a better rate. Your debt-to-income ratio (DTI) : This is calculated by dividing your monthly debt payments by your monthly income before taxes to come up with a percentage. The higher your DTI, the higher your rate could be. The down payment size and Loan-to-Value (LTV): Your down payment is the percentage of the home’s price you will put down. The LTV is the percentage of a home’s sales price that equals your mortgage. The type and term of loan program options: Your loan officer will walk you through different loan options based on what you qualify for. Mortgage rates can vary between different loan products and programs. Even after you find a home you love, other things can have an impact too. For example: A mortgage rate buydown: This helps you get a lower mortgage rate, and by extension, a lower monthly payment, by paying an upfront cost. Sometimes a seller, builder, or another party may even offer to cover that cost themselves as an incentive for you to buy. Seller concessions : Sellers are allowed to pay buyer closing costs according to most loan program guidelines. Seller-paid closing costs can add up to thousands of dollars, which can free up some cash for you to increase your down payment, pay down debt, or make other financial adjustments to try to get a better rate. Your First Step? Getting Pre-Approved. If you want to know if your number could be higher or lower than the headlines on social, you need to talk to an expert. A simple conversation with a loan officer can help you determine when you’ll be ready to buy, how much you can borrow, and of course, what your real rate will be. Your lender may recommend a pre-qualification and pre-approval: Pre-qualification is a general estimate of what you might be able to borrow based on self-reported information. On the flip side, pre-approval is actually a conditional commitment from a lender based on verified information. Just know that, of the two, the pre-approval process gives you a more accurate picture of your options than pre-qualification. Bankrate gives a quick comparison so you can see why: 
September 23, 2026
Data centers probably weren't on your list of things to think about when buying or selling a home. School districts? Sure. How close you are to family? Absolutely. A large building full of computer servers down the road? Probably not. But that may be changing. Data centers are popping up in more communities across the country. And as they do, buyers and homeowners are starting to wonder what having one nearby could mean for everything from home values to utility bills. So, let's get into what the data actually says. Because there's a lot more nuance here than if they’re “good” or “bad.” Data Centers Are Showing Up in a Lot More ZIP Codes According to Realtor.com , back in 2015, only about a dozen ZIP codes had a large data center. But by the first half of 2026, that number had climbed to more than 100 – and it's projected to rise even further by the end of the year ( see graph below ):
September 23, 2026
Summer's winding down, and if you've been thinking about selling , you might be wondering if you missed your chance. Better to wait until next year or even next spring, right? Not so fast. About one in three of all home sales happen in the last four months of the year. Fall Is Busier than You Think Data from the National Association of Realtors (NAR) shows around a third of existing home sales happen in the final four months of the year. And that share has grown every year since 2023 ( see graph below ):
Show More